Top signals · Discovery

What deserves a closer look?

See the stock ideas gaining credible support, understand the case, and decide what deserves a closer look.

Daily edition

Friday, September 25, 2026

3 signals · 165 candidates reviewed

01
CRWDContested

CrowdStrike

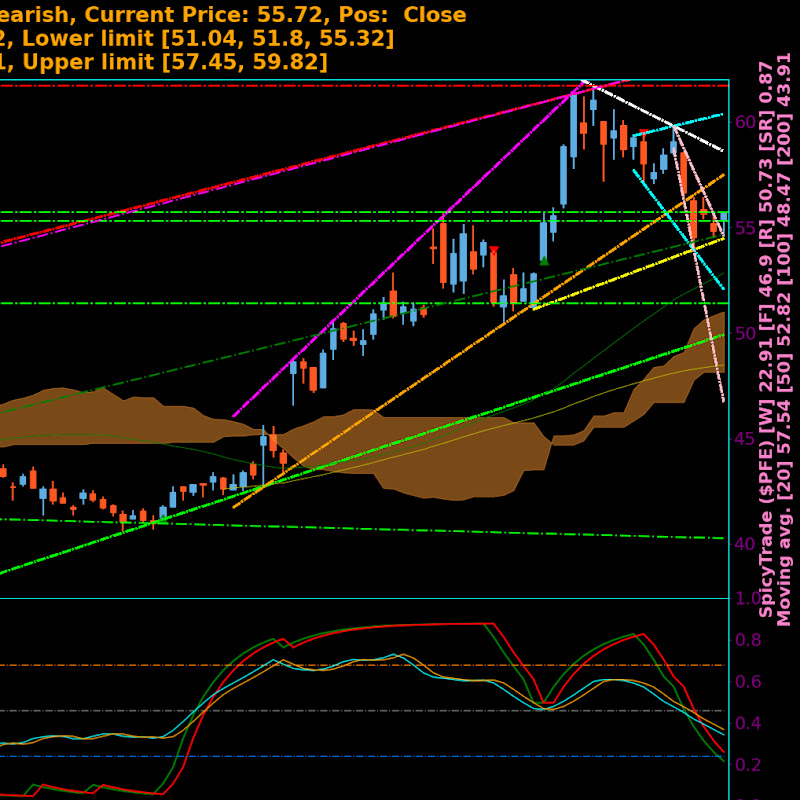
CrowdStrike faces intense competition while technical momentum suggests institutional accumulation of shares.

The dispute centers on valuation, valuation risk, and position disclosure.

6 independent sources·YouTube + Instagram + Reddit

6 independent views3 platformsNew idea2/4 bull/bear splitOutcome pending

The case

Valuation concerns

bearish

Multiple sources argue that CrowdStrike is overvalued, citing high P/E ratios, high price-to-sales multiples, and the belief that growth is already priced in.

3 support

Technical momentum

bullish

CrowdStrike exhibits strong technical indicators, including trading above major moving averages and positive momentum indicators, suggesting institutional accumulation.

1 support

AI-driven growth

bullish

CrowdStrike's strategic partnerships with companies like Nvidia and OpenAI are viewed as a significant growth catalyst for its AI-powered cybersecurity platform.

1 support

Competitive pressure

bearish

The cybersecurity market is highly competitive, with concerns that rapid industry changes and numerous competitors threaten CrowdStrike's leadership position.

1 support

Why now

Spicy Trade Stock Technical Analysis published a new primary call on Sep 23.

What could break it

No tracked source stated a clear invalidation condition.
02
NKEContested

Nike

Nike clashes over brand equity resilience and the potential for earnings recovery.

The dispute centers on valuation and position disclosure.

6 independent sources·YouTube + Reddit

6 independent views2 platformsNew idea4/2 bull/bear splitOutcome pending

The case

Valuation attractiveness

mixed

Some investors view Nike as undervalued based on forward P/E ratios and price corrections, while others note risks or overvaluation in DCF models.

2 support · 1 mixed

Management and brand strategy

mixed

Critics argue that management has damaged brand equity and pricing power through poor strategic decisions, while proponents maintain the brand remains resilient.

1 support · 1 challenge

Technical and earnings outlook

mixed

The stock faces conflicting outlooks, with some citing a potential bottom and earnings catalysts, while others highlight a severely damaged chart.

1 support · 1 challenge

Why now

Parkev Tatevosian, CFA published a new primary call on Sep 22.

What could break it

  • Potential for a 10% drop if earnings are bad.
  • Management's strategic failures will continue to negatively impact the stock price.
Sources and track records6 records
Parkev Tatevosian, CFA

YouTube · Sep 22

+8.6% average · 103 resolved calls

Nike stock looks slightly undervalued overall, despite a DCF valuation suggesting it's slightly overvalued.

“Comprehensively, I would say Nike stock looks slightly undervalued.”
Read source
u/lies_are_comforting

Reddit · Sep 18

Deep author analysis

Nike is near its bottom and represents a 'buy and hold' opportunity for safe returns, with potential for a significant jump following upcoming earnings.

“It further shows signs that Nike is very close to its bottom. The market is red today and Nike stock is flat.”
Read source

-2.7% average · 1 resolved calls

Nike, trading below $40 with a P/E of 18 and a 4% dividend yield, is presented as a potential value opportunity after a significant price correction.

Read source
u/Tripleawge

Reddit · Sep 9

Deep author analysis

Nike's management has destroyed long-term brand equity and pricing power by prioritizing short-term volume over scarcity, making it a poor investment.

“management chose to try to more aggressively monetize that scarcity through volume rather than preserve it as long term brand equity.”
Read source
Adriconomics

YouTube · Sep 7

+0.2% average · 2 resolved calls

Nike is approaching a valuation that interests the creator after years of being too expensive, with the stock near its 2022 IPO price but with improved cash flow.

“Now, we are finally approaching a valuation that has my interest. But if you don't believe Nike will turn around, the natural winner will be on running shoes. Topline growth is decelerating, but we are very close to IPO prices of 2022, but now the cash flow is real. Valuation is compelling.”
Read source
Wide Moat Research

YouTube · Sep 4

New directional call

Nike's stock is viewed very negatively, described as potentially the worst chart in the market, down 80% from its highs, and the company is considered terrible.

“I It's really sad for me to see where Nike share price has gone. I mean, that's like one of my favorite brands. I I don't I think I'm like an old man because then I feel like the younger kids like don't love Nike like I did, but Nike and Jordan was so cool growing up. And that stock, I mean, you want to look at like that might be the worst chart in the entire market. I mean, Nike is down, I think, 80% from their highs. Uh it's it's a terrible company and and we're seeing that play out in the retail space right now.”
Read source
03
TSLAContested

Tesla

Tesla hinges on robotaxi technology success and the sustainability of operating margins.

The dispute centers on valuation, margins, and regulatory event.

6 independent sources·YouTube + Instagram + Reddit

6 independent views3 platformsNew idea3/3 bull/bear splitOutcome pending

The case

Valuation and earnings expectations

mixed

Tesla's current stock price is viewed by some as overvalued, trading at high multiples relative to current earnings and cash flow, while others see significant long-term upside potential.

2 support · 1 challenge

Autonomous technology and robotaxi potential

mixed

The successful rollout of robotaxi and autonomous driving technology is cited as a primary driver for future valuation, though some question the current state of these technologies.

2 support · 1 challenge

Tesla Semi economic viability

bullish

The Tesla Semi is argued to have superior unit economics compared to diesel trucks, providing a potential growth catalyst.

1 support

Operating margin performance

bearish

Concerns exist regarding the company's current operating margins and their ability to support the current valuation.

2 support

Why now

Meet Kevin published a new primary call on Sep 23.

What could break it

No tracked source stated a clear invalidation condition.
Sources and track records6 records
Meet Kevin

YouTube · Sep 23

+0.8% average · 4 resolved calls

Tesla's Semi truck offers superior unit economics and operational benefits compared to diesel trucks, making it a compelling investment with a rapid adoption potential.

“So, the payback period within five years is a good investment. Typically, these trucks or these semi-trucks last for 10 to 15 years. The breakeven point at that stage is one-third to one-half of the life of that asset that's still being depreciated.”
Read source
investwithgigi

Instagram · Sep 14

+5.0% average · 44 resolved calls

Tesla is viewed as overvalued, trading at 192x forward earnings for a robotaxi story that hasn't shipped.

“you're paying 192 times forward earnings for a robo story that hasn't even shipped yet”
Read source
u/Organic-Amoeba-7520

Reddit · Sep 13

Deep author analysis

Tesla is positioned to dominate the ride-hailing market by removing driver costs and utilizing extensive vehicle data for autonomous navigation.

“they have insane amounts of data from Tesla cars to further train their cars in harsh conditions like snow.”
Read source

+1.9% average · 2 resolved calls

Tesla is considered a dead company with no growth, likely to be merged with SpaceX in the future.

Read source
Future Investing

YouTube · Sep 5

+7.8% average · 1 resolved calls

Tesla stock is posited to be at least a 10x opportunity in the next 5-10 years, contingent on the successful rollout of robotaxi and bot technology.

“From where I sit, it's at least a 10x. Not financial or investment advice, it's at least a 10x. So, now the question becomes, what's the likelihood that robotaxi and bot, if they materialize in the next 5 to 10 years, what does that do to to valuation?”
Read source
Dividend Talks

YouTube · Sep 1

+16.9% average · 26 resolved calls

Tesla is ranked seventh due to its stock price assuming extraordinary opportunity, with current operating economics not supporting the valuation and implying significant downside.

“And my base case discounted cash flow value sits at $264 against a market price today of 363. Well, that implies around 27% downside to the fair value. No margin of safety.”
Read source

Continue the research

Create an account to see more signals and editions.

Create account